Acorns: Invest For Your Future
AcornsFinanceVerified
- 77.07K Reviews
- 4.7
- Downloads
- 10,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
When I first considered an investing app, I wanted a clear way to begin without having to choose individual stocks or learn every market term first. Acorns: Invest For Your Future takes an automated, small-contribution approach: purchases can be rounded up and the difference invested, while recurring contributions let you build a routine. That can make the first step feel manageable, but it is still investing, not a guaranteed savings plan. Your balance can change with the markets, so I’d use the app only with money I can leave invested and afford to see fluctuate.
Acorns is a finance app from developer Acorns. It is free to download, rated for Everyone, and has a 4.7 average from around 387,000 ratings, with over 10 million installs. Those figures suggest it has reached a broad audience, but they are not a substitute for checking whether its approach suits your own budget and goals. The app was released in 2014, and version 4.183.0 supports devices running Android 10 or later.
What the small-contribution approach means
The central idea is to make investing feel less like a one-time leap and more like a habit. Instead of asking you to start by choosing a company and deciding when to buy its shares, the app presents an automated route built around a portfolio. For a first-time investor, that can remove some intimidating decisions. The trade-off is less control: this is not designed to be a detailed research terminal or a place to manage a hand-picked stock portfolio.
Rounding up everyday spending may sound effortless, but the money still comes from your finances. I’d think of it as a contribution method, not free growth: the rounded amounts add up because they are drawn from your spending, and investment performance is never certain. If your budget is tight, even small deductions can matter. A sensible first check is whether you can cover regular bills and keep a cash cushion before directing extra money toward investing.
First setup: make the choices deliberately
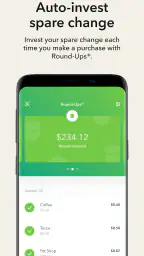
Diving into Acorns is pretty straightforward, which is great because who wants a complicated start when managing money? Once you download the app, the setup is as easy as pie. You link your bank account, and voilà, you're ready to roll. The app rounds up your purchases to the nearest dollar and invests the difference. It's like saving without even thinking about it.
Even with a simple onboarding flow, I would slow down at the points where the app asks me to connect an account and make investment choices. Before linking a bank, I’d read the connection and account information shown in the app and make sure I recognize the account I’m selecting. Then I’d look carefully at the portfolio choices and the risk level associated with them rather than picking the first option just to finish setup. A quick start is useful only if you understand what you have switched on.
I’d also decide what role round-ups should play before relying on them. They can suit someone whose spending is fairly steady and who likes small, frequent contributions. They may be less comfortable for someone whose income or essential expenses vary from week to week. In that case, starting with a recurring amount you have deliberately budgeted can be easier to anticipate than letting daily purchases determine the contribution flow.
Other Stories to Read




Your first meaningful action
For me, the first useful milestone would not be watching a balance move; it would be setting a contribution pattern I can keep without having to undo it later. The app offers recurring investments, so I’d choose a schedule and amount that fit the budget I already use. If I’m unsure, I’d start conservatively, check how that amount feels across a normal spending cycle, and adjust only after seeing the effect on my cash flow.
A realistic example: imagine I buy coffee on the way to work and make several other card purchases during the week. Round-ups can turn those transactions into small investment contributions without requiring me to open the app each time. But if an unusually expensive week is coming, I would not treat the automation as untouchable. I’d review the settings and the linked account balance, then decide whether my routine still makes sense. The practical win is a repeatable process, not a promise that small deposits will quickly become a large fund.
That distinction also helps answer a common first-timer question: should I use round-ups or scheduled contributions? They serve different habits. Round-ups follow eligible spending; a recurring investment is a planned amount on a chosen cadence. A person with predictable pay and a clear monthly budget may prefer the control of a planned contribution, while someone who struggles to remember regular transfers may value the purchase-linked approach. You can think about which one fits your real routine rather than assuming you must use every option.
Using Acorns with a clear plan
Simplifying Investing
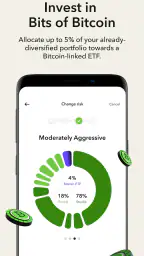
Now, I’m not a financial guru, but Acorns breaks down investing into bite-sized pieces. The app offers a few diversified portfolios to choose from, all based on your personal financial goals and risk tolerance. You can feel all fancy picking the one that fits your style. Plus, you get to learn a bit about stocks and bonds along the way. It’s a win-win!
For a newcomer, the useful question is not which portfolio sounds most impressive; it is whether its risk profile matches the purpose and time horizon for the money. Money needed soon is usually a poor fit for market exposure, because a downturn can arrive just when you need to withdraw. By contrast, someone building a longer-term investing habit may be more comfortable accepting that values can rise and fall. I’d treat the portfolio selection as a decision to revisit when my circumstances change, not a personality quiz that permanently settles the matter.
This is where Acorns differs from a standard savings account and from a self-directed brokerage app. A savings account is generally the more straightforward place for near-term cash and emergency reserves; it does not expose that money to the same investment-market movement. A brokerage can offer more direct control over investments, but it asks you to make more choices and do more research. Acorns sits between those experiences: it automates contributions and uses diversified portfolios, which is convenient, but it also means less hands-on control and no guarantee of returns.
Features That Stand Out
One of my favorite features is the "Found Money" section. Who doesn’t love a little extra cash? When you shop with Acorns’ partner brands, you get bonus investments added to your account. It’s like getting rewarded for your usual shopping habits. And let’s not forget about the recurring investment option. You can set aside a specific amount every day, week, or month. It’s the perfect way to build a nest egg without even noticing.
I’d treat partner-linked bonuses as an occasional extra rather than a reason to buy something. A useful rule is to compare the purchase with what I would have chosen without the offer. If it nudges me into spending more, the investment bonus may not make the decision worthwhile. The more reliable habit is the contribution plan I can afford on its own; any shopping-linked addition should be incidental, not the foundation of the strategy.
There is also a practical trade-off between convenience and visibility. Automatic contributions can reduce the number of decisions I have to make, but that same convenience can make it easy to forget how much is moving out of a spending account over time. I’d check the account activity periodically, especially after changing a schedule or linking a new spending pattern. That small review helps catch a contribution routine that no longer matches my budget.
A Look at the Interface
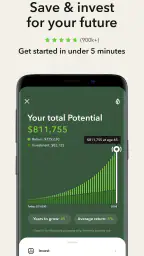
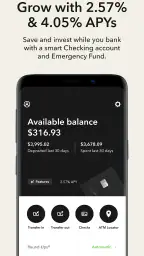
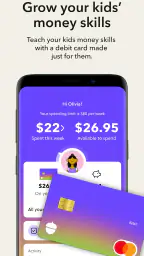
The interface is clean and user-friendly. I mean, nobody wants to stare at a cluttered screen when managing their finances, right? The dashboard gives a quick glance at your account balance, recent transactions, and investment performance. It’s all laid out in a way that even a newbie like me can understand.
A quick dashboard is handy for orientation, but I would avoid judging an investing plan by a short stretch of performance. A balance can move for reasons unrelated to whether my contribution habit is sensible, and frequent checking can tempt a new investor to react to ordinary ups and downs. I’d use the screen to confirm that contributions and transactions look as expected, then review the bigger question—whether the plan still suits my goals—less impulsively.
If I were comparing this with a spreadsheet or a bank’s built-in savings tools, I’d focus on what I actually need to monitor. A spreadsheet gives me flexibility but depends on my own updates and discipline. A savings feature may keep cash accessible without asking me to think about a portfolio. Acorns is more useful when I specifically want an automated route into investing and am comfortable checking an investment account rather than treating it like a fixed-value savings pot.
Security and Peace of Mind
Security is a big deal when it comes to money, and Acorns doesn’t disappoint. They use heavy-duty encryption to keep your data safe. Plus, your investments are insured up to $500,000 by the SIPC, which adds an extra layer of peace of mind. It’s like having a digital safe for your investments.
I’d still keep security habits on my side of the screen: use a strong, unique password, protect access to the device, and review account activity if something looks unfamiliar. It is also worth understanding what investment protection does and does not mean. Protection against certain brokerage failures is not the same as insurance against a market decline, so it cannot promise that the value of an investment will stay level. That distinction matters when deciding whether money belongs in an investment app or somewhere more stable and immediately accessible.
Who will get the most from it
I think Acorns is strongest for someone who wants a guided, low-maintenance entry into investing, has enough breathing room in their budget to contribute, and does not want to choose individual securities. It may also work for a person who already saves consistently but wants a separate, automated investing habit alongside that routine. The app’s rounded purchases can make the process feel approachable, while recurring contributions give a more deliberate option for people who prefer to plan.
I would skip it, or at least wait, if I were carrying urgent expenses, needed every dollar for near-term bills, or wanted instant access and a stable balance for emergency money. I’d also look elsewhere if I wanted detailed investment research, direct stock selection, or close control over every trade. In those cases, a conventional cash account or a self-directed brokerage may fit better, depending on whether access and stability or control and choice are the priority.
So, who exactly is Acorns for? If you’re someone who wants to dip your toes into investing without diving headfirst into the stock market, this app might be your new best friend. It's perfect for folks who are just starting out, or for those who simply want to make their spare change work harder.
However, if you’re looking for a full-fledged investment tool with in-depth analysis and stock picking, you might find Acorns a tad basic. But that’s the beauty of it—it’s not trying to be something it’s not. It’s all about ease and accessibility.
The Final Verdict
After giving Acorns a spin, I have to say, it’s a pretty nifty way to get into investing. It takes the intimidation factor out of the equation, making it approachable for anyone. Plus, watching your small change grow into a bigger sum over time is pretty satisfying. So, if you’re looking to start investing without the fuss, Acorns might just be the app to kickstart your financial journey. It’s like having your own little financial sidekick, always ready to help you save and grow your future.
My practical recommendation is to begin with a small plan you understand, confirm how contributions affect your everyday cash, and give the routine time rather than expecting a quick result. Acorns: Invest For Your Future can make the act of beginning feel less intimidating, but the best first success is not a particular balance: it is knowing what you are contributing, why you chose that approach, and when you might need the money. If that sounds like the kind of structure you want, it is worth considering; if your priority is cash access or full investment control, another route will probably serve you better.
Highlights
- Easy-to-use interface for beginners.
- Automatic round-ups simplify saving.
- Diverse portfolio options available.
- Low fees compared to traditional investing.
- Educational resources for new investors.
Limitations
- Limited control over individual investments.
- No tax-loss harvesting features.
- Withdrawals can be slow to process.
- Requires a monthly subscription fee.
- Lacks advanced trading options.
Frequently Asked Questions
01What is Acorns and how does it work?
Acorns is a micro-investing app that helps users save and invest small amounts of money automatically. By linking your credit or debit card, Acorns rounds up your purchases to the nearest dollar and invests the spare change into diversified portfolios. It's an easy way to start investing without needing significant upfront capital.
02Is Acorns safe to use for investing?
Yes, Acorns is safe and secure for investing. It uses bank-level security and data encryption to protect your personal and financial information. Additionally, Acorns accounts are SIPC insured for up to $500,000, which includes a $250,000 limit for cash claims, providing an extra layer of security.
03What are the fees associated with using Acorns?
Acorns offers a tiered subscription model with fees ranging from $1 to $5 per month, depending on the services you choose. The basic plan, Acorns Lite, costs $1 per month and includes core investing features. Higher tiers offer additional features like retirement accounts and checking accounts.
04Can I withdraw money from my Acorns account at any time?
Yes, you can withdraw funds from your Acorns investment account at any time without penalty. However, it may take a few business days for the funds to transfer to your bank account. Keep in mind that withdrawing money may affect your investment goals and overall portfolio performance.
05What types of investments does Acorns offer?
Acorns invests in a range of ETFs (Exchange-Traded Funds) that cover various asset classes, including stocks and bonds. The app offers diversified portfolios tailored to your risk tolerance and financial goals. This allows users to benefit from broad market exposure with a balanced approach to investing.


